
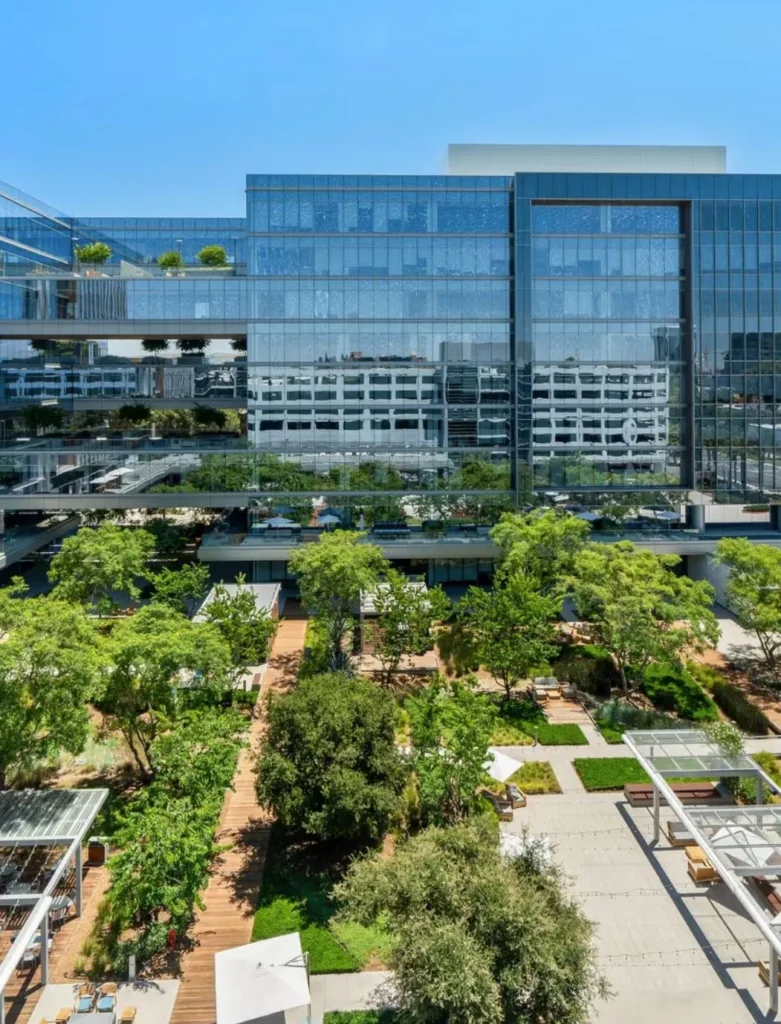
Irvine Office Market: Setting the Context
Irvine is one of Southern California’s largest office markets. The greater John Wayne Airport office market alone has 38 to 40 million square feet. This Market Outlook focuses on 1. John Wayne Airport/Irvine Business Complex (IBC), 2. Newport Center and 3. the balance of Newport Beach.
Important Note About the Data
These figures are largely pulled from Newmark, CBRE, Colliers and Cushman & Wakefield, which do not always define these smaller submarkets in exactly the same way. For that reason, we use the most relevant available data to identify trends in rents, vacancy, absorption and tenant activity while avoiding comparisons between statistics that cover materially different geographic areas.
Office Market Outlook: 2027
The office market surrounding John Wayne Airport continues to recover from the elevated vacancy and tenant downsizing that followed the pandemic. Recent brokerage reports indicate improving absorption and declining vacancy in important portions of the market, although conditions continue to vary significantly by building quality and location.
Class A buildings continue to capture a disproportionate share of tenant demand. Companies are generally favoring better buildings, amenities and locations while often taking less space than they occupied historically. This flight to quality continues to create a significant divide between top-tier Class A properties and older office buildings competing for tenants.
For this Outlook, the primary indicators we follow are Class A asking rents, vacancy, quarterly and year-over-year absorption, and leasing activity within specific industries. Current reports show Class A asking rents in the broader Airport market generally in the $3.45 per square foot per month full-service. Rents have been moving modestly higher while vacancy has been trending lower.
Financial services, professional and business services, and legal firms remain important sources of office demand around John Wayne Airport. Technology, healthcare and other specialized industries also continue to contribute to leasing activity.
Office-to-Residential Conversion
Another trend affecting the 2027 outlook is the removal of older office properties for residential development. Unlike normal leasing absorption, these projects can permanently reduce the amount of competing office inventory.
Several projects are moving through the Airport/IBC area. At MacArthur Court, plans call for replacing 126,837 square feet of existing low-rise office with 700 apartments, while the two major office towers remain. At 1500 Quail Street, an approved plan would demolish an 86,000-square-foot office building for 100 for-sale townhomes. At 1901 Main Street, plans call for converting the first four floors of an existing eight-story office building into 66 apartments, with another nine townhomes constructed on the property. Interestingly, the remaining four floors would continue as office space.
The Von Karman Corporate Center is another potentially significant change. A proposal calls for 426 for-sale homes on portions of the approximately 25-acre office campus. The existing campus contains nine buildings totaling roughly 450,000 square feet.
These projects are at different stages, ranging from proposed and entitled to approved. Although small relative to the overall office inventory, they represent an emerging trend toward removing older office product and introducing additional residential uses within the Airport/IBC.
John Wayne Airport / Irvine Business Complex
The John Wayne Airport Area and Irvine Business Complex are treated as one office market.
This is a diverse mixed-use Class A and Class B market with a growing residential component. Demand continues to favor high-quality Class A space, while older properties face greater competition and often provide stronger negotiating opportunities for tenants.
The 2026 numbers reinforce that split. Class A asking rents in the broader Airport market are approximately $3.45 per square foot per month full service, while Class A vacancy is approximately 18%. Vacancy has been trending lower throughout 2026, and positive absorption has been the story for nearly all of 2026.
Leasing activity remains concentrated in better-quality core or prime buildings. Financial services, professional services and legal firms have been among the active tenant groups, reinforcing the Airport/IBC’s position as a service-oriented corporate location.
The spread between highly amenitized Class A properties and older Class A remains substantial, creating distinctly different negotiating environments within the same market.
Newport Center
Newport Center is separate from the Airport/IBC because it is a distinct premium Class A office market centered around Fashion Island. Tenants typically pay a substantial premium for location, parking and other occupancy costs.
As a reference point, the broader Newport Beach office market averaged approximately $3.93 per square foot per month full service in 1H 2026, with total vacancy around 11%. Newport Center’s premium Class A properties command rents above the broader Newport Beach average.
Residential development is also beginning to affect Newport Center. The Irvine Company received zoning approvals allocating as many as 1,500 residential units within North Newport Center. Plans associated with 100 and 190 Newport Center Drive contemplate approximately 600 residences, although those units should be considered planned rather than under construction. Separately, a project at 210 & 300 Newport Center Drive proposes two 22-story residential buildings containing 150 condominiums although appeals are in process.
Medical office is an important component of Newport Center, but it behaves differently from conventional office space. Medical tenants generally invest heavily in their locations and tend to remain in place longer, resulting in less tenant movement than in the traditional office market. Asking rents for desirable medical space can also exceed conventional office rents because of specialized improvements, location and limited availability.
For tenants, both conventional and medical office remain opportunity markets, but they should be evaluated separately because turnover, build-out costs and lease economics can be quite different.
Newport Beach Office Outside Newport Center
The remainder of Newport Beach includes properties along the Pacific Coast Highway corridor and smaller, more fragmented office concentrations throughout the city. Building quality, rents, parking and tenant mix can vary considerably from property to property.
The best available data for Newport Beach includes Newport Center, making it difficult to assign a precise vacancy or asking-rent figure to the balance of Newport Beach. Through 2026, the broader Newport Beach market averaged approximately $2.95 per square foot per month full service with vacancy around 11%.
Medical office will continue to be identified separately when relevant rather than combined with conventional office statistics or treated as a separate geographic submarket.
Outlook for Tenants
Heading into 2027, conditions are improving for landlords and vacancy has been trending lower. Outside of the renovated and highly amenitized Class A projects, the greatest leverage remains across Airport Area/IBC and Newport Beach among older Class A and Class B Buildings
For tenants willing to compare multiple alternatives, differences in rents, tenant improvements, free rent, parking and other concessions can produce substantially different occupancy costs even among buildings located near each other.